Silver City Location and Payment Plans: Your 2026 Affordability Guide
Two questions decide most property purchases: where is it, and how will I pay for it? Get both right and the rest usually follows. In 2026, buyers researching the Silver city location quickly discover that its position on the Rawalpindi–Islamabad corridor pairs naturally with flexible, installment-based financing. This guide ties those two threads together so you can judge affordability with clear eyes rather than guesswork.
Whether you are a salaried first-time buyer or a cash-rich investor, understanding how location value and payment structure interact will sharpen every decision you make.
Why Location Drives the Whole Equation
Location is the single factor you cannot renovate. You can upgrade a kitchen, repaint a facade, or add a floor, but you cannot move a plot closer to the motorway. That permanence is exactly why seasoned buyers study connectivity before anything else.
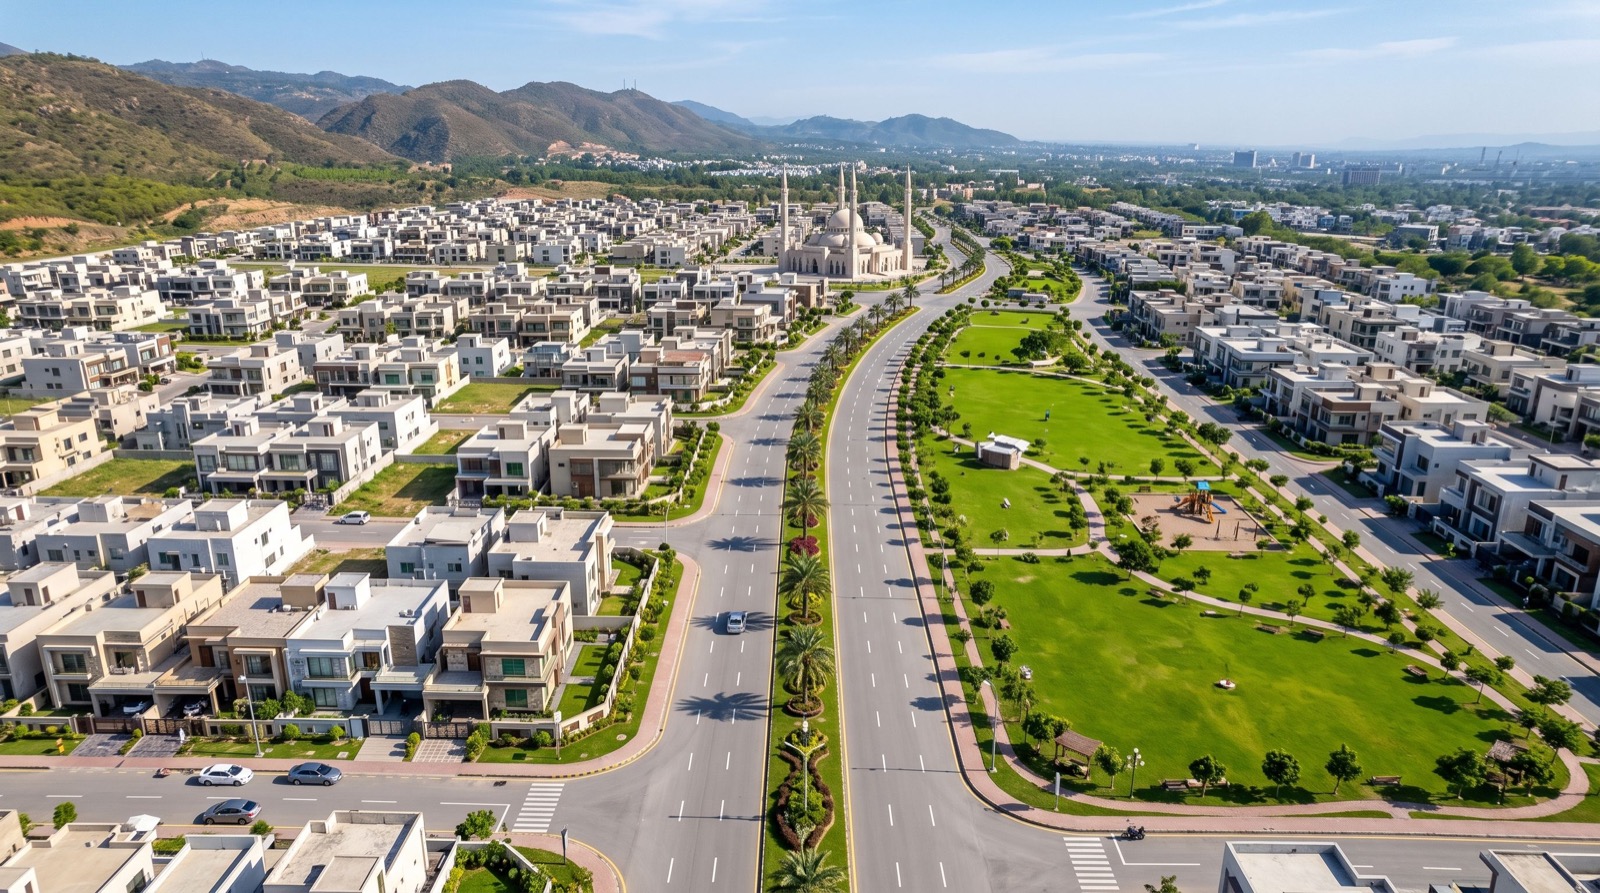
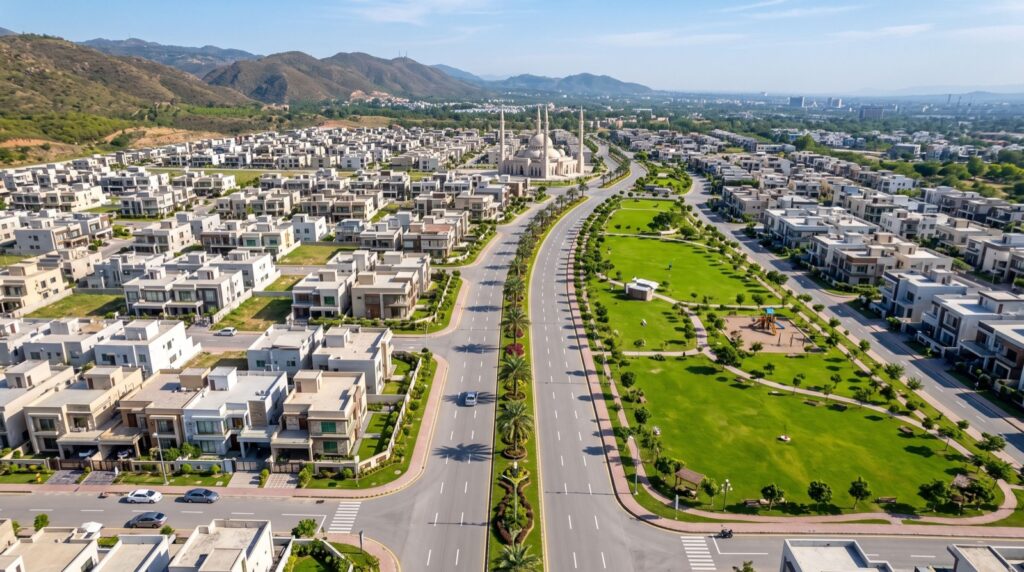
The Silver City position offers several location advantages that support both livability and resale:
- Direct access to major motorway and ring-road links serving the twin cities.
- Reasonable distance to the new Islamabad International Airport.
- Proximity to education and healthcare hubs that families prioritize.
- Surrounding development momentum that lifts demand over time.
Transport economists consistently link accessibility to land value; research summarized by the World Bank Urban Development program shows how connectivity and infrastructure investment shape property markets in growing cities. In short, a well-connected address is not just convenient, it is a financial asset.
How far is the location from the twin cities’ core?
Travel time matters more than raw distance. A plot that is a few extra kilometers out but sits on a fast, uncongested route can beat a nominally closer property stuck behind daily bottlenecks. When you assess the location, measure it in minutes during peak hours, not just on a map.
Understanding Payment Plans in 2026
Installment financing has transformed access to property for middle-income buyers. Rather than paying the full price upfront, you spread it across a down payment and scheduled installments. Reviewing the official Silver City payment Plan is the best way to see current structures, but the mechanics below apply broadly.
A typical plan has three components:
- Down payment — an initial percentage, often 15–30%, that secures the plot.
- Monthly or quarterly installments — spread across two to four years.
- Confirmation or possession charges — milestone payments tied to development stages.
The appeal is cash-flow friendliness: you commit a manageable sum now and pay the balance from ongoing income while the asset, ideally, appreciates.
Lump-Sum vs. Installment: Which Wins?
Both approaches have merits, and the right one depends on your liquidity and discipline.
| Factor | Lump-Sum Payment | Installment Plan |
|---|---|---|
| Upfront cash needed | Full price | Down payment only |
| Typical discount | Often available | Rare |
| Cash-flow strain | High at purchase | Spread out |
| Opportunity cost | Capital locked | Capital stays liquid |
| Best for | Cash-rich buyers | Salaried buyers |
Lump-sum buyers often negotiate a discount and avoid the mild premium baked into installments. Installment buyers keep capital free for other uses and reduce single-payment risk. Neither is objectively better, it depends on whether your advantage is cash or cash flow.
How to Budget Honestly for a Plot
Affordability is more than the sticker price. Before you commit, build a realistic budget with help from reliable local experts who can benchmark current rates and hidden costs.
- Down payment plus an emergency buffer, never drain your savings to zero.
- Installment affordability — keep total property payments within roughly a third of monthly income.
- Transfer and registration fees, which add a few percent to the headline price.
- Development and possession charges that fall due at milestones.
An original budgeting tip: model your plan against a worst-case month, a delayed salary, a medical cost, a rate rise, and confirm you can still meet the installment. If the plan only works when everything goes perfectly, it is too tight. Build slack in before you sign.
What happens if I miss an installment?
Most plans impose a late surcharge and a grace window; repeated defaults can risk cancellation and partial forfeiture. Always read the default clause before signing, and if you foresee trouble, contact the developer early, renegotiation is far easier before a payment is formally missed.
Putting Location and Payment Together
The smartest buyers in 2026 evaluate location and payment as one combined decision. A superb location on an unaffordable plan leads to stress and possible default; an easy plan in a weak location ties up money in a stagnant asset. The sweet spot is a well-connected plot on a plan your income comfortably absorbs.
Run the two analyses side by side. Score the location for connectivity and growth, then score the payment plan for affordability and flexibility. A property that passes both tests is the one worth pursuing.
Mistakes Buyers Make With Payment Plans
Installment plans feel accessible, and that accessibility sometimes lulls buyers into avoidable errors. Recognizing these pitfalls in advance keeps your purchase on solid ground through the full payment term.
The most common missteps in 2026 include:
- Ignoring milestone charges and budgeting only for the monthly installment.
- Overcommitting income, leaving no cushion for emergencies or rate changes.
- Skipping the default clause, then being surprised by surcharges or forfeiture.
- Assuming guaranteed appreciation will cover a plan they cannot otherwise afford.
Each of these errors shares a root cause: optimism substituting for arithmetic. A payment plan is a multi-year financial commitment, and it deserves the same scrutiny you would give a long-term loan. Run the numbers conservatively, and let the math, not the sales enthusiasm, decide whether a plan fits.
A practical habit worth adopting is to keep a simple payment calendar from day one, marking every installment and milestone charge with its due date and amount. Buyers who track their schedule rarely miss a payment, while those who rely on memory or sporadic reminders are the ones who stumble into late surcharges. The discipline costs nothing and protects everything you have committed.
Frequently Asked Questions
Is the Silver City location good for long-term value?
Its position on the Rawalpindi–Islamabad corridor, with motorway and airport access plus surrounding development, supports steady long-term demand. Location permanence makes connectivity one of the most reliable drivers of future value.
How much down payment do I need in 2026?
Down payments commonly range from about 15% to 30% of the plot price, depending on the plan and category. Always confirm the current figure from the official payment plan and keep an emergency buffer beyond it.
Are installment plans more expensive than paying in full?
Usually slightly, since installments spread risk and cost for the developer. Lump-sum buyers often secure a discount, while installment buyers trade that saving for cash-flow comfort and liquidity, a worthwhile exchange for many salaried buyers.
Can I switch from an installment plan to lump-sum later?
Often yes. Many developers let you clear the remaining balance early, sometimes with a discount for doing so. Confirm the early-settlement terms in writing before you commit, as policies vary between plans.
Conclusion
Buying property well in 2026 comes down to marrying the right Silver City location with a payment plan your finances can genuinely sustain. Study the connectivity, read the plan’s fine print, budget for the worst month rather than the best, and lean on trustworthy local guidance. Do that, and you turn a major purchase into a confident, well-structured step toward lasting value.